Roofers Specialty — Insurance & Risk Management, powered by The Duncan Group
Downtown Austin skyline at dusk along Congress Avenue

Insurance Brokerage & Risk Management Consulting Designed Especially for Roofing Contractors, by People Who Know & Love Their Industry.

Roofers Specialty is the specialized roofing practice of The Duncan Group, combining insurance brokerage, risk management, claims advocacy, underwriting strategy and technology for roofing contractors.

Headquartered in Austin, Texas. Serving roofing contractors across a growing national footprint. Outside Texas? We still want to hear from you — our nationwide expansion is actively underway.

Why roofing is different

Two roofing contractors with the same revenue can be entirely different risks.

Roofing is not a standard construction class, and it is not one class at all. Work mix, height, geography, labor model, subcontractor dependency, fleet, contracts and loss history change both the exposure and the set of carriers willing to compete for it.

The variables below routinely move an account between markets, structures and pricing tiers — before anyone looks at premium.

Work mix

Residential, commercial or mixed — and whether the work is new construction, reroof, repair or service.

Height and access

Steep-slope, low-slope, multistory and the access methods used to reach the work.

Geography

Wind, hail, wildfire and jurisdictional litigation environment, state by state.

Storm work

Surge hiring, unfamiliar crews and out-of-state work compress controls at the worst moment.

Subcontractor dependency

How much work is transferred, and whether the risk actually transferred with it.

Fleet

Vehicle count, radius, driver selection and the severity potential excess markets price for.

Labor model

Employee, 1099 and subcontract labor treated very differently by audit and by workers' compensation.

Contractual risk transfer

The indemnity and insurance obligations accepted upstream, before any loss occurs.

Completed operations

Roofing claims often surface years after a job closes — where many programs are weakest.

Safety systems

Whether controls exist, and whether they exist as evidence an underwriter can evaluate.

Loss history

Frequency, severity, reserve development and what the trend suggests about the operation.

Hot work and equipment

Torch, kettle, crane and hoist operations that change both the exposure and the market set.

The Roofers Specialty Risk Map

Where roofing risk actually lives.

Select an area of the operation to see the exposure behind it.

Exposure

People

Crew tenure, supervision, classification and injury exposure sit behind workers' compensation cost and much of the liability picture.

The Risk Diagnostic

Before an insurance carrier evaluates your business, we do.

Roofing risk cannot be understood from revenue and payroll alone. The diagnostic examines eight dimensions of the operation and the program that finances it, so that weaknesses are found while there is still time to address them.

  • Insurance Program

    What the current program actually covers.

  • Operations

    How the work is actually performed.

  • Claims

    What the loss history is telling the market.

  • Subcontractors

    Whether risk transfer is real or assumed.

  • Fleet

    Where severity most often lives.

  • Safety

    Whether the program is documented or informal.

  • Contracts

    What you have agreed to carry.

  • Underwriting

    How the company will be presented.

The Roofers Specialty Method

Diagnose. Improve. Position. Negotiate. Place. Manage.

A continuous cycle, not a once-a-year transaction. Select a stage to see what happens in it.

  1. Diagnose
  2. Improve
  3. Position
  4. Negotiate
  5. Place
  6. Manage

Each cycle informs the next. The loop does not reset at renewal.

Understand the current program, exposures, operations, claims, controls, contracts and market position before anything is marketed.

Premium Negotiation Strategy

Same exposure data. Different underwriting story.

Premium is not a random number produced from payroll and revenue. Underwriters are pricing uncertainty. Better information, stronger evidence and a disciplined market strategy reduce that uncertainty — and create real competition for the account.

We do not claim premiums can simply be negotiated downward. We build the case that allows an underwriter to price what is actually there.

What the carrier already knows

  • $25M revenue
  • $4M payroll
  • 35 vehicles
  • 65% subcontracted
  • Loss history
  • States of operation

What a strong presentation also explains

  • Subcontractor qualification standards
  • Completed operations controls
  • Additional insured requirements
  • Written safety programs
  • Telematics and fleet monitoring
  • MVR standards and enforcement
  • Return-to-work program
  • Contract review procedures
  • Claims corrective actions
  • Management and supervisory experience
  • Loss trends and what changed
  • Operational and risk-management initiatives

Two contractors submit the same numbers. Only one of them has been explained.

What does an underwriter actually see?

Revenue tells an underwriter scale, not character.

Revenue sets the rating basis for general liability and frames the size of the account. It says nothing about how the work is performed, who performs it or how the company controls what happens on a roof.

  • What the data shows: exposure base, growth rate, account size
  • What may be missing: project mix, self-performed versus subcontracted work, customer type
  • How we build context: a revenue breakdown by operation, project type and contract structure

Roofing Risk Management

Insurance is one component of a larger system.

Eleven practice areas sit behind the program. Six of them account for most of what moves a roofing contractor’s cost of risk.

  • Subcontractors

    Prevent subcontractor failures from becoming your loss history.

  • Fleet

    Manage one of the exposures most closely scrutinized by excess carriers.

  • Claims

    Turn claims history into operating intelligence.

  • Workers' Compensation

    Manage reserves, experience modification, return-to-work and loss trends.

  • Contracts

    Understand the liabilities being accepted before a loss occurs.

  • Safety

    Turn operating controls into evidence underwriters can evaluate.

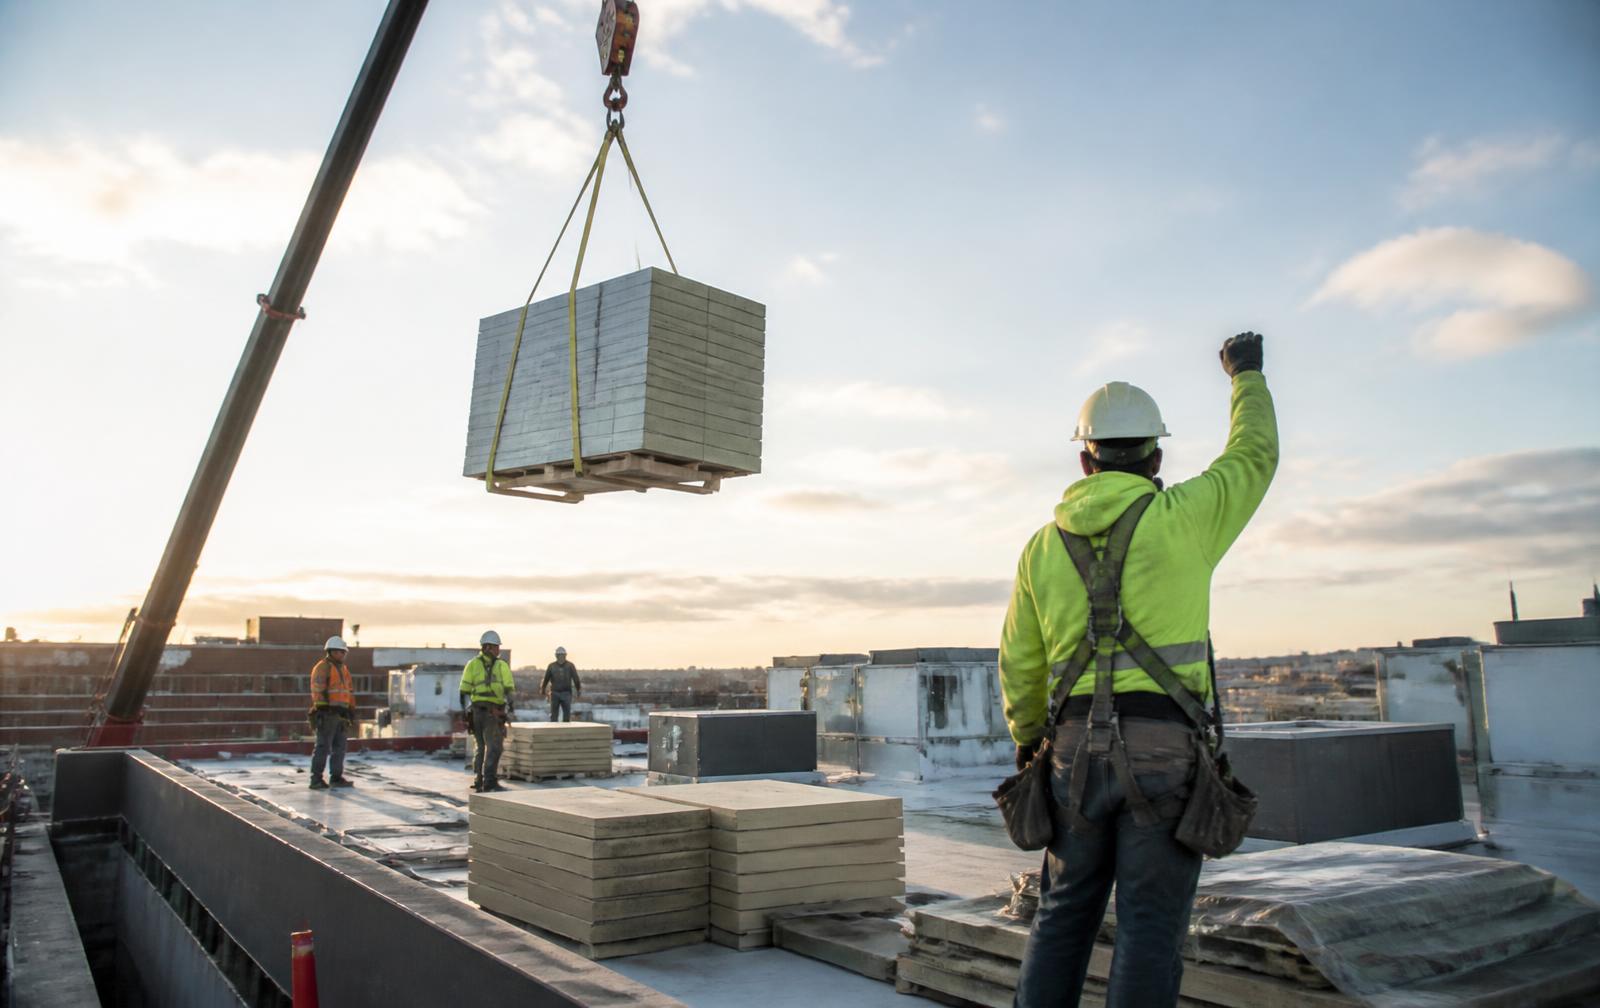
Roofing crew staging insulation board on a commercial rooftop while a crane hoists materials

Subcontractor Risk Center

A certificate of insurance is not a subcontractor risk-transfer program.

A certificate records that a policy existed on a date. Risk transfer is built from written agreements, indemnification, endorsement language, verification and enforcement — and it fails quietly until a claim tests it.

  • Written subcontract agreements
  • Indemnification
  • Additional insured — ongoing operations
  • Additional insured — completed operations
  • Primary and noncontributory
  • Waiver of subrogation
  • Workers' compensation verification
  • Actual endorsement review
  • Policy exclusion review
  • Expiration monitoring and compliance enforcement

Claims Advocacy

When the claim happens, your broker matters.

We do not simply report claims. We help organize the facts, coordinate the parties, monitor the process, and use what each loss teaches us to strengthen the client’s risk-management strategy.

Reporting, documentation, coverage communication, carrier and adjuster coordination, counsel coordination, risk-transfer tenders, reserve review, claim strategy, large-loss coordination and loss-trend analysis. Roofers Specialty advocates for the client; carriers determine coverage.

  1. 01

    Incident

  2. 02

    Notice

  3. 03

    Investigation

  4. 04

    Coverage Position

  5. 05

    Reserve

  6. 06

    Resolution

  7. 07

    Post-Claim Review

And back into the diagnostic

  1. Risk
  2. Control
  3. Insurance
  4. Claim
  5. Analysis
  6. Improved risk

Each cycle informs the next. The loop does not reset at renewal.

Loss documentation, contracts and loss runs during a roofing claim review

RiskAtlas

Your insurance program should not live in somebody's inbox.

RiskAtlas gives Roofers Specialty clients a modern interface for accessing and managing insurance information while working with the Duncan advisory team.

We are an insurance and risk-management practice, not a software company. RiskAtlas is infrastructure supporting the client experience — nothing more, and nothing less.

RiskAtlas — Client Workspace

Illustrative view

Policies in force

11

Open claims

3

Days to renewal

118

  • General LiabilityIn force
  • Workers' CompensationIn force
  • Commercial AutoIn force
  • Umbrella / ExcessIn force
  • Inland MarineIn force

Annual Service Calendar

Risk management does not begin 60 days before renewal.

A structured annual framework, adapted to each client’s renewal date, operations and priorities. Timing is illustrative rather than identical for every account.

  1. Q1

    Program implementation

    Binding, endorsements, certificates, internal onboarding and RiskAtlas setup are completed deliberately rather than administratively.

  2. Q1

    Claims and loss review

    Open claims, reserves and recent loss activity are reviewed with the client and, where useful, with the carrier.

  3. Q2

    Risk-management initiatives

    The agreed control priorities for the year — subcontractor, fleet, safety, contract — move into execution.

  4. Q2

    Exposure review

    Revenue, payroll, fleet, project mix and geography are updated so the program reflects the business as it is now.

  5. Q3

    Contract and subcontractor review

    Upstream contract obligations and downstream subcontractor requirements are compared against the program in force.

  6. Q3

    Pre-renewal Risk Diagnostic

    The diagnostic is run again while there is still time to act on what it finds.

  7. Q4

    Underwriting strategy

    The narrative, supporting documentation and submission package are built around the year's evidence.

  8. Q4

    Market engagement

    The markets that fit the operation are approached directly and with context.

  9. Q4

    Premium Negotiation Strategy

    Structure, terms, credits and economics are negotiated across competing markets rather than accepted as quoted.

  10. Renewal

    Proposal

    Options are compared on coverage, structure and total cost of risk — not premium in isolation.

  11. Renewal

    Renewal implementation

    The program is implemented, documented and loaded into RiskAtlas, and the cycle begins again.

Who we serve

Roofing contractors from approximately $5M to $250M+ in revenue.

Operational profile matters more than size. We work with contractors whose exposure, complexity or growth makes the quality of their insurance and risk program a genuine business issue.

  • Residential roofing
  • Commercial roofing
  • Mixed residential and commercial
  • Regional contractors
  • Multistate contractors
  • Storm restoration
  • Commercial low-slope
  • Metal roofing
  • Architectural sheet metal
  • Self-performing contractors
  • Subcontractor-heavy contractors
  • Private-equity-backed platforms
  • Multi-location roofing organizations

Not every roofing company is a fit for this practice, and we will say so early rather than late.

Case studies

Documented engagements, published only from verified data.

Every engagement is recorded in the same structure — problem, diagnostic, strategy, execution, outcome. We do not publish illustrative results, projected savings or composite accounts.

  1. 01

    Problem

  2. 02

    Diagnostic

  3. 03

    Strategy

  4. 04

    Execution

  5. 05

    Outcome

Roofing Risk Intelligence

Original research on roofing risk, insurance markets and claims.

Explore Roofing Risk Intelligence
  • Insurance Market
  • Risk Management
  • Claims
  • Subcontractor Risk
  • Fleet
  • Workers Compensation
  • Safety
  • Legal & Litigation
  • Underwriting

Insurance Market

Why roofing contractors are seeing pressure on umbrella capacity

Excess markets have narrowed the terms they offer roofing risks. The contractors holding their limits are the ones who can document subcontractor controls and driver quality.

Wyatt Duncan · September 2026

  • Subcontractor Risk

    A certificate of insurance is not a risk transfer program

    Wyatt Duncan · September 2026

  • Workers Compensation

    The experience modification is a document, and documents contain errors

    Wyatt Duncan · September 2026

  • Fleet

    Fleet is where roofing programs are being repriced

    Wyatt Duncan · September 2026

Start where the problem is

Most conversations begin with one specific issue.

Roofers Specialty

A specialized practice of The Duncan Group

The Duncan Group provides insurance, risk management, employee benefits and specialty advisory capabilities across complex commercial industries. Roofers Specialty is its dedicated roofing practice — the same institutional infrastructure, applied to a single trade.

Visit The Duncan Group

Start with an analysis.
Not a quote.

Before approaching the insurance market, understand how your current program, operations, claims, subcontractors, contracts, fleet and risk controls will be viewed by underwriters.

Coverage availability, terms and pricing vary by account, carrier, underwriting result and jurisdiction. Nothing here is an offer of coverage or a guarantee of premium, terms or claim outcome.